
DeSoto Drywall Pros Blog • DeSoto, TX • November 6, 2026
Does Homeowners Insurance Cover Water Damaged Drywall in Texas?
Does homeowners insurance cover water damaged drywall? In Texas, it depends on your policy and what caused the water. Sudden and accidental damage, like a burst pipe, is usually covered. A slow leak, and flood water from outside, are usually not covered. Call (469) 933-0245.
Finding wet drywall is stressful enough. The next question is always the same: will insurance pay for this? The honest answer is that it depends — on what caused the water, how long it went on, and what your policy actually says. This guide explains the Texas rules in plain words, what is usually covered and what is usually not, and how to document your damage so a claim has the best chance. It is general information, not insurance advice, and it does not guarantee coverage for any one claim.
24/7 • DeSoto, TX 75115 & 75123 • About 25 km around DeSoto
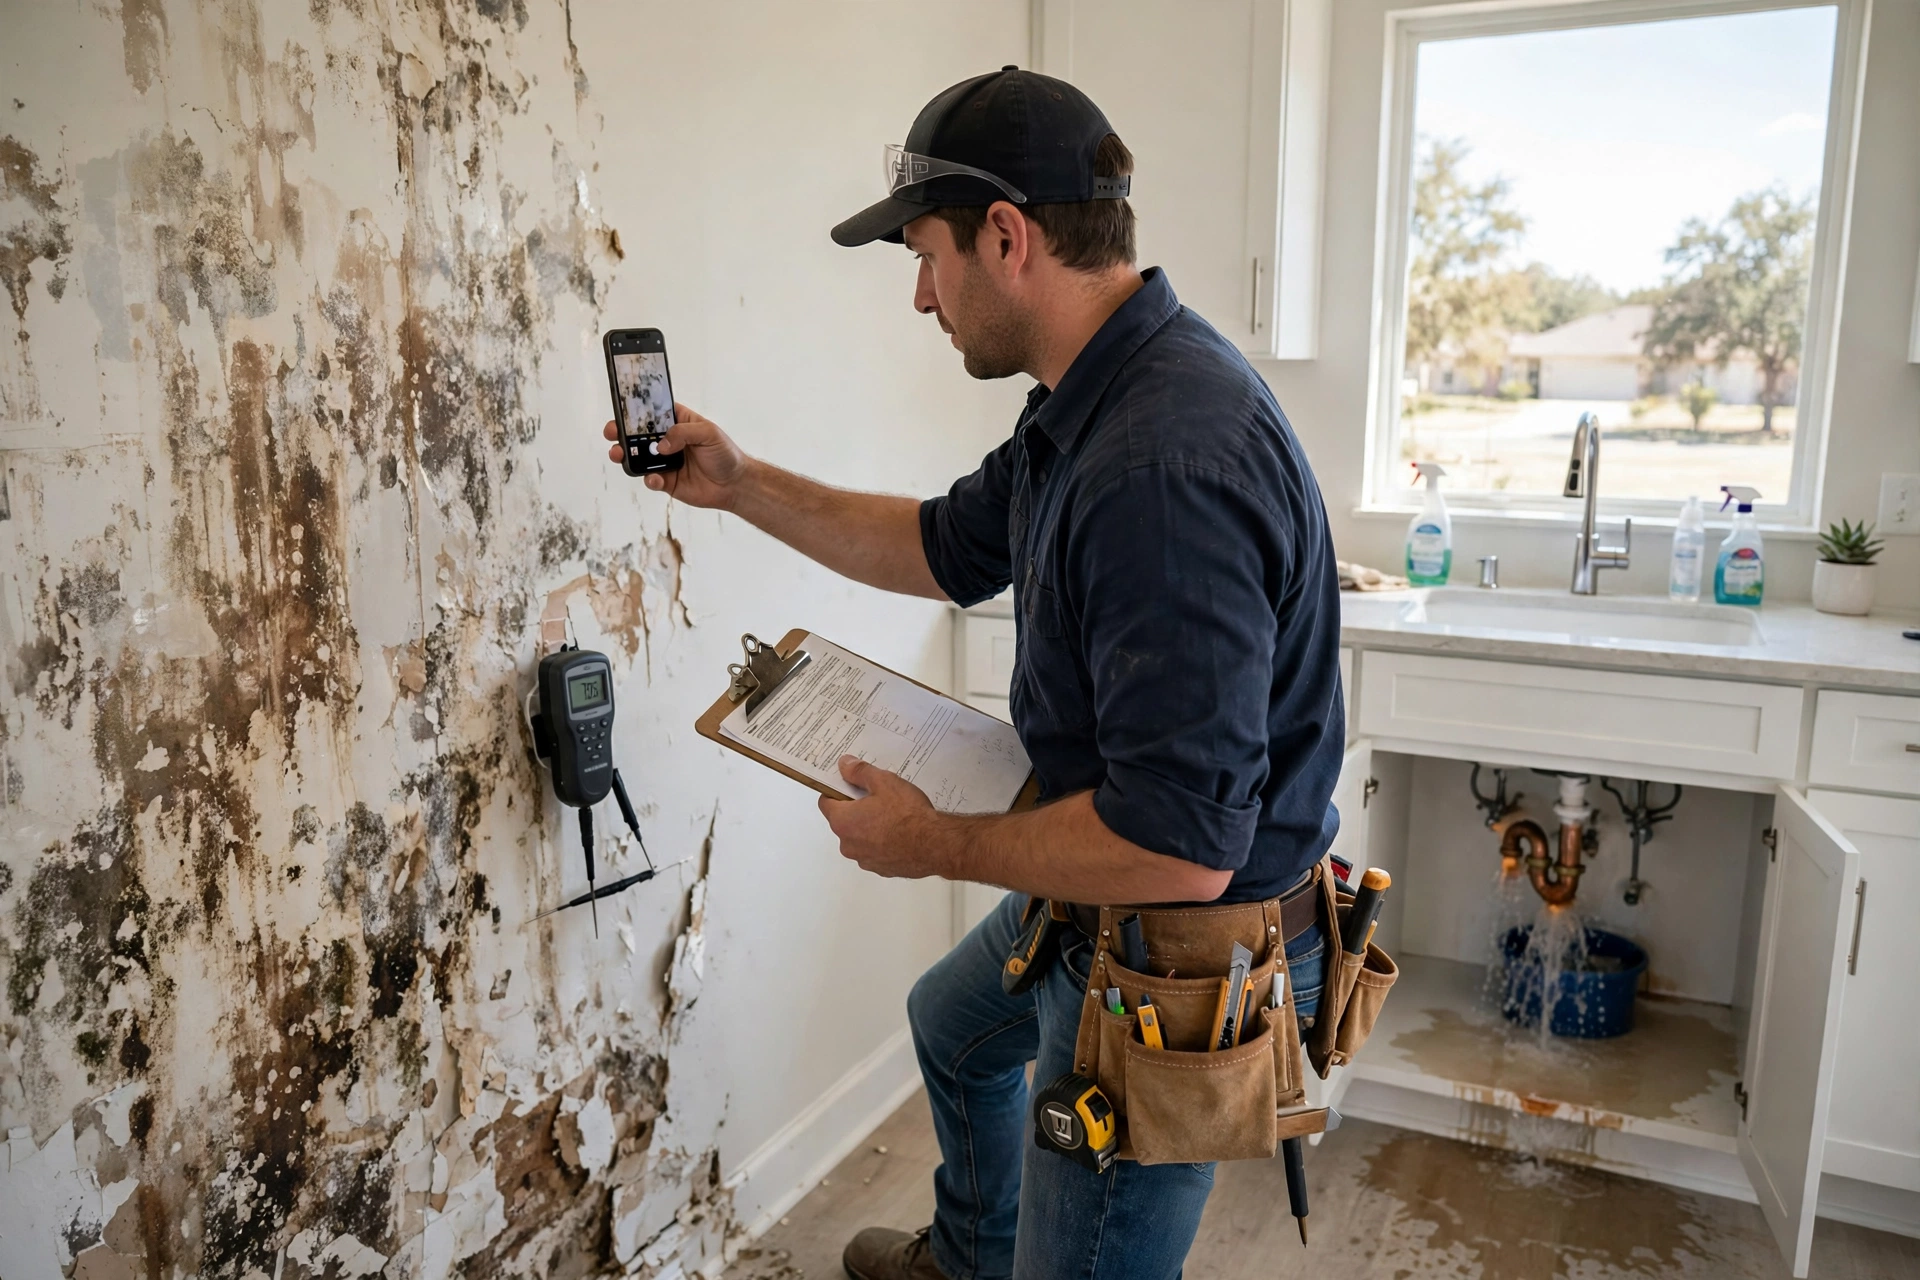
The Texas Rule
Does Homeowners Insurance Cover Water Damaged Drywall in Texas?
The rule Texas insurers use is simple to say and hard to apply: sudden and accidental water damage is usually covered; gradual damage and flood damage are usually not. The Texas Department of Insurance puts it the same way — most policies cover water damage that happens suddenly and by accident, like a burst pipe or a broken washer hose, but they do not cover damage from gradual leaks or seepage. You can read the Department’s own guidance at tdi.texas.gov.
What does sudden and accidental mean in practice? It means water that arrived all at once, without warning, from a source inside the home. A supply pipe that bursts overnight. A water heater that fails. A washing machine hose that snaps. An upstairs toilet that overflows while you are out. In each case, the homeowner did nothing wrong and could not have seen it coming. That is the kind of loss a homeowners policy is built for.
Gradual damage is the opposite. A pipe that dripped behind a wall for six months. A roof that leaked a little every time it rained, for a year. A shower seal that failed slowly, letting water into the wall a drop at a time. Insurers treat this as maintenance — something the homeowner should have found and fixed. It is the most common reason drywall water damage claims are denied, and it is also the most common kind of hidden damage, because a slow leak behind drywall can go unnoticed for months. If you suspect a hidden leak, read our guide on how to tell if drywall is wet behind the wall before it becomes a bigger problem.
There is one more distinction that matters in Texas: the difference between water that comes from above and water that rises from below. Rain that comes in through a roof damaged by wind or hail is often covered, because the storm damaged the building first and the rain followed. Water that rises from the ground — storm runoff, a rising creek, water pooling against the house and coming in under a door — is flood damage, and a standard homeowners policy does not cover it. Flood damage needs separate flood insurance. The same wet drywall can be covered or not covered depending on which direction the water came from, which is why the cause matters more than the damage itself.
Covered or Not
What Texas Homeowners Insurance Usually Covers — and What It Does Not
Usually covered: A burst pipe that soaks a wall and ceiling overnight. A failed water heater. A broken appliance hose. A toilet overflow. Rain that enters through a roof or window damaged by wind or hail. In these cases, the insurer typically pays to repair the damage the water caused — the ruined drywall, the wet insulation, the damaged flooring and belongings — minus your deductible.
Usually not covered: A leak that went on for weeks or months. Damage from wear, corrosion, or poor maintenance. Flood water from outside, including storm runoff and rising water. Sewer backup, unless you bought separate sewer backup coverage. Mold that grew because a leak was left alone, rather than mold that grew from a covered sudden event.
The part most homeowners get wrong: the insurer usually pays for the damage, not for the thing that failed. If a pipe bursts and ruins your drywall, the policy typically pays to replace the drywall, but not to replace the pipe itself. If a water heater fails and floods a room, the policy typically pays for the floor and walls, but not for a new water heater. This surprises a lot of people, and it is worth knowing before you talk to the adjuster.
Mold is a special case. Mold that grows from a covered sudden event — a burst pipe that soaked the wall before it could be dried — is often part of the same claim. Mold that grew because a slow leak was ignored is usually treated the same way as the leak itself: not covered. And even when mold is covered, many policies cap how much they will pay for mold cleanup. If mold is part of your damage, read our guide on how fast mold grows on wet drywall and get the area assessed quickly.
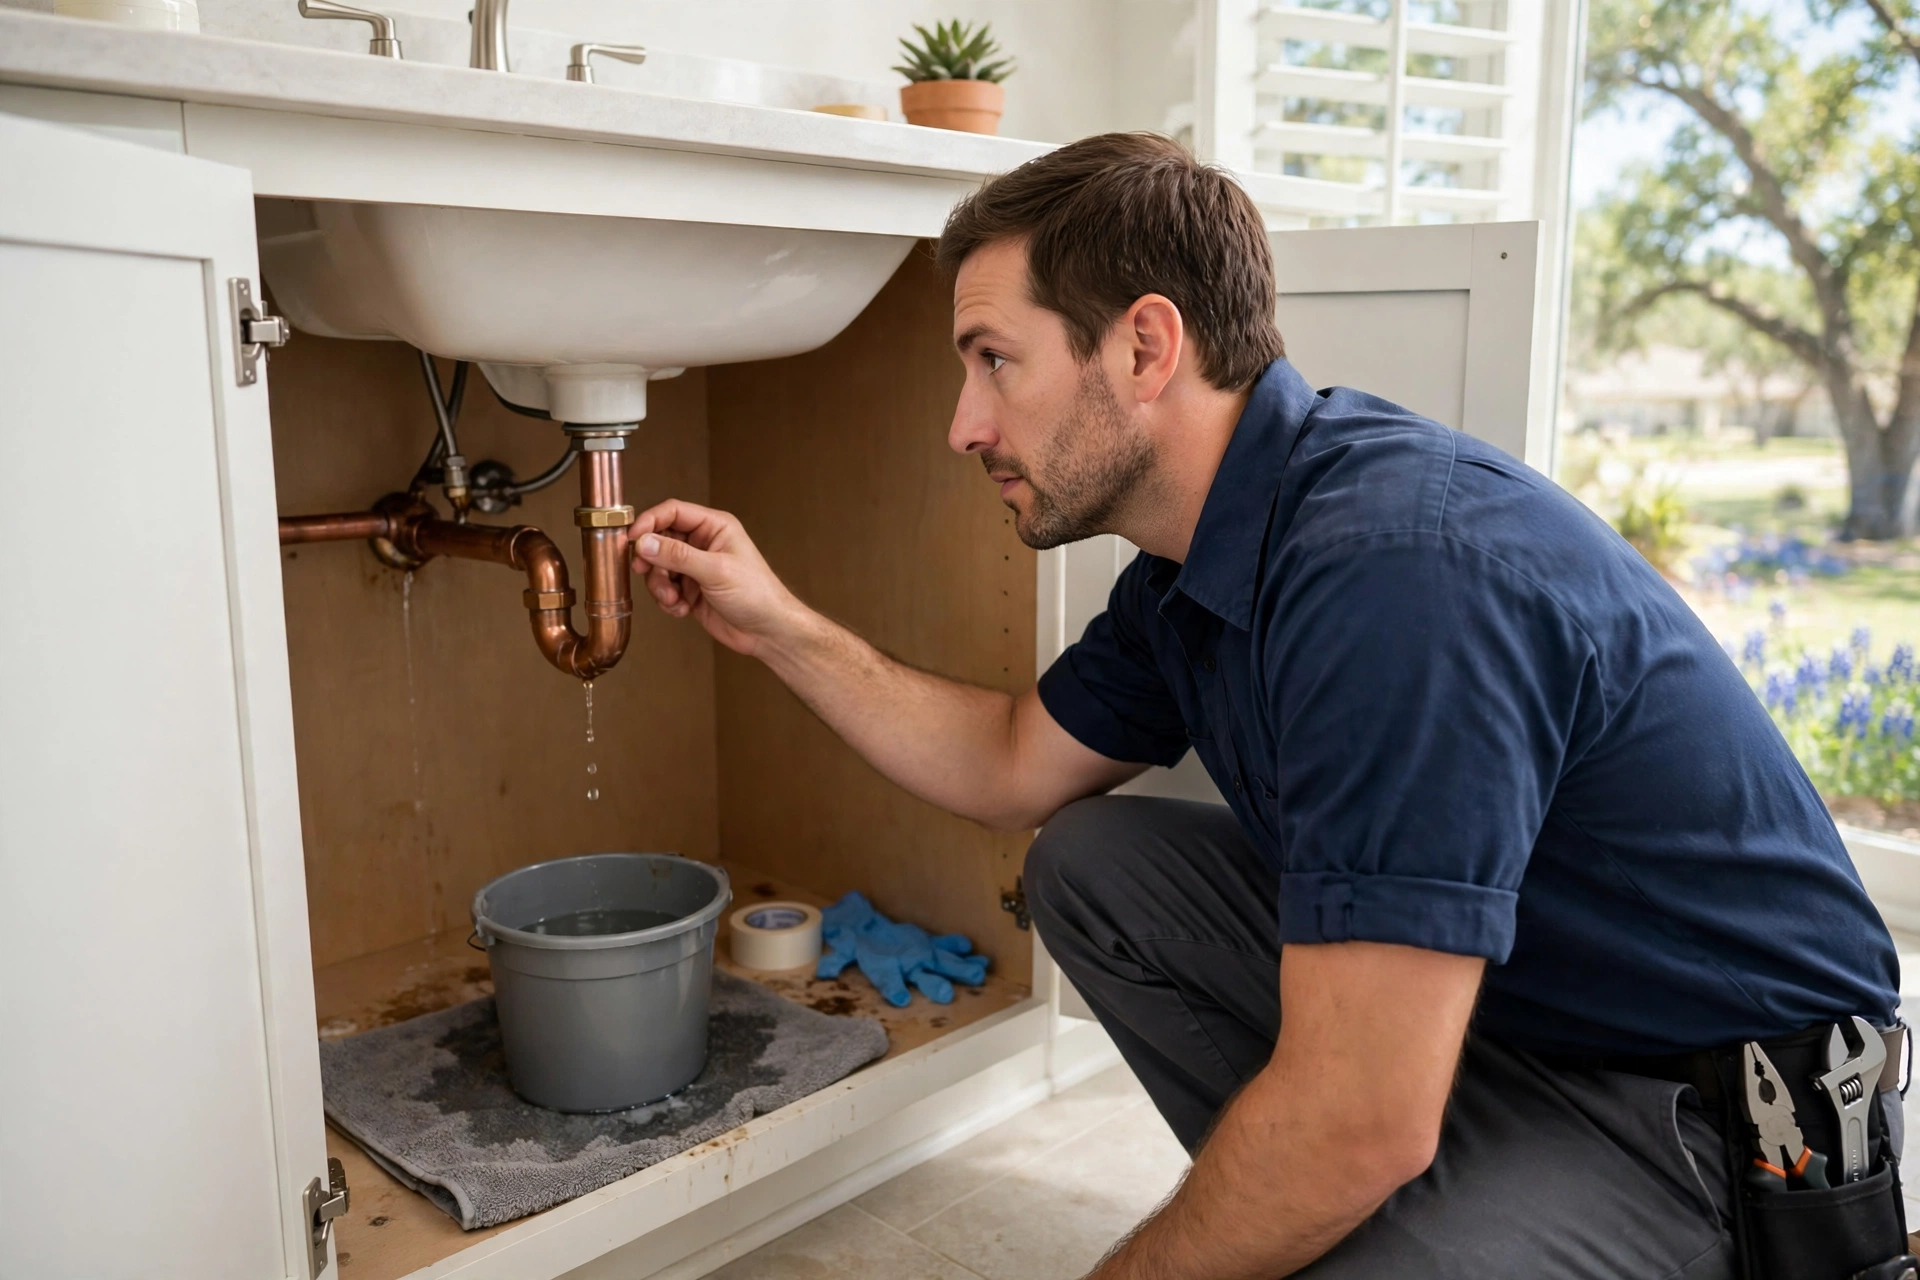
One thing to be clear about: none of this guarantees coverage for your claim. Every policy is different, and the wording in yours is what decides it. If your insurer denies a claim and you think it was wrong, the Texas Department of Insurance can explain your options. What we can do is document the damage properly and repair it right.
Document It Right
How to Document Water Damaged Drywall for an Insurance Claim
Good documentation is the difference between a smooth claim and a fight. Adjusters work from evidence, and the best evidence is gathered before anything is torn out. Here is what to collect, in order.
1. Photos and video, before anything moves. Photograph the damage from across the room and close up. Get the stain, the soft spots, the bubbling paint, and any sagging. Video a slow walk-through of every affected room. Photograph the water source too — the burst pipe, the failed hose, the roof damage. Take more photos than you think you need. You cannot go back and photograph drywall that has already been removed.
2. The date and the story. Write down when you found the damage, what you saw, and what you think caused it. If a pipe burst overnight, say so. If a storm damaged the roof on a specific date, say so. A short, honest timeline helps the adjuster match the damage to a covered event.
3. Moisture readings in writing. A photo of a stain shows what the wall looked like. A moisture meter reading shows how wet it actually was, and how far the water travelled. We take pin and pinless readings across the affected walls and record them. Those readings also decide how much drywall has to come out — which is why our drywall drying and moisture detection service in DeSoto, TX is part of every insurance job we do.
4. A written repair estimate. Get a detailed estimate that lists what has to be removed, what has to be dried, and what has to be rebuilt. A line-by-line estimate gives the adjuster something to work with, and it protects you from a low offer that leaves out the drying or the texture matching. Our insurance documentation and rebuild help in DeSoto, TX covers exactly this — photos, readings, and a written scope of work.
5. Keep damaged materials until the adjuster has seen them. Do not throw wet drywall away before the adjuster visits, unless it is a health risk or the adjuster tells you to. If you must remove it for safety — a sagging ceiling, for example — photograph it first, from several angles, and keep a sample if you can.
And report the damage promptly. In Texas, homeowners are generally expected to report water damage soon after finding it, and to take reasonable steps to stop more damage — shut off the water, move belongings out of the way, and get the area drying. Waiting weeks to report a leak you knew about can hurt a claim, even if the leak itself was sudden.
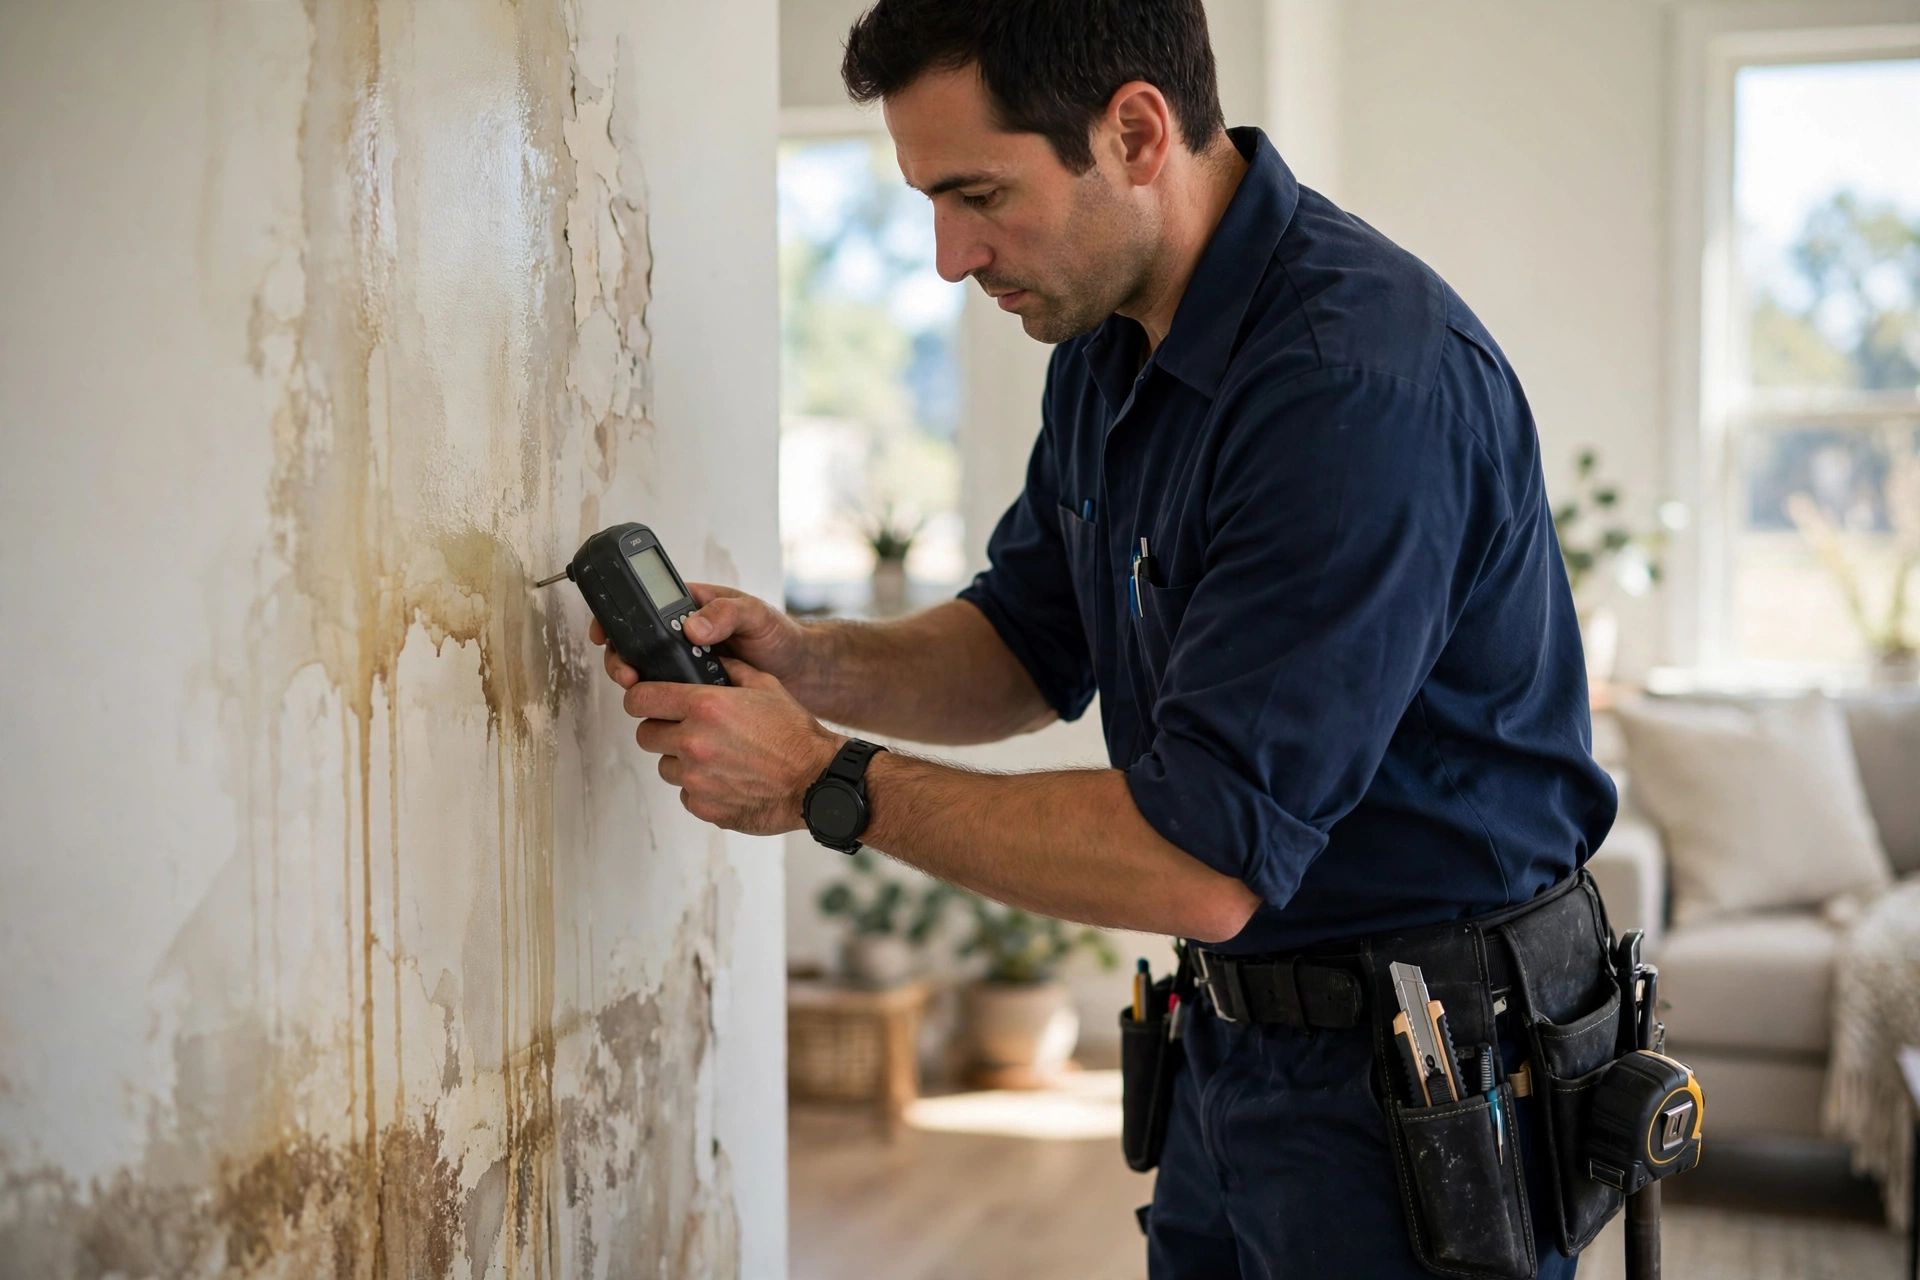
Costs & Deductibles
What Will It Cost You? Deductibles and Typical Repair Ranges
These are typical U.S. ranges, not a DeSoto quote. Your out-of-pocket cost depends on your deductible and how much drywall is wet.
| Job | Typical U.S. range |
|---|---|
| Stain-only repair (no removal) | $150 – $400 |
| Partial drywall replacement | $350 – $1,500 |
| Full ceiling replacement | $1,000 – $3,000+ |
| With mold involved | $2,500 – $6,000 |
How the deductible works: if your deductible is $1,000 and the repair costs $1,400, the insurer typically pays $400 and you pay $1,000. If the repair costs less than your deductible, it is usually cheaper not to claim at all — and a small claim can still count against you at renewal. That is why a lot of DeSoto homeowners pay for small stain-only repairs themselves and save the claim for the big ones. For the full breakdown, read our guide on how much it costs to replace water damaged drywall in DeSoto, TX. Call (469) 933-0245 for an exact quote on your repair.
DeSoto, TX
Water Damage Claims in DeSoto, TX Homes
DeSoto sits 12 miles south of Dallas, in southern Dallas County, on I-35E and I-20. Most homes here are one-story and split-level brick homes built in the 1970s and 1980s, on slab foundations. The claims we see most often come from burst pipes in winter cold snaps, roof leaks after hail and wind storms, AC drain leaks in summer, and appliance hoses that fail without warning. After a big storm, the question is almost always the same: did the rain come in through storm damage, or did the water rise from outside? The answer decides whether the claim is covered, so it pays to document the roof and the water path carefully.
We work across DeSoto, in ZIP codes 75115 and 75123, and in neighborhoods including The Meadows, Thorntree, Eagle Crest, Brandonwood, Frost Farms, Amber Terrace, Hidden Lakes Estates, and Summit Parks. If your drywall got wet and you are thinking about a claim, call (469) 933-0245 before anything is torn out. We will photograph the damage, take moisture readings, and give you a written estimate you can hand to your adjuster. If you are weighing repair against replacement, read our guide on can water damaged drywall be saved in DeSoto, TX. For the DeSoto area page, see water damaged drywall repair in DeSoto, TX, or visit our homepage to see all our services. If a pipe burst is what caused your damage, our guide on drywall repair after a burst pipe in DeSoto, TX walks through what happens first.
Related Articles
Keep reading — these answer the next questions most homeowners ask.
Related Services
Not sure which one you need? Call us.
FAQ
Does Homeowners Insurance Cover Water Damaged Drywall — Questions We Hear in DeSoto
Does homeowners insurance cover water damaged drywall?
It depends on your policy and what caused the water. In Texas, sudden and accidental water damage — like a burst pipe — is usually covered. Gradual leaks, poor maintenance, and flood water from outside are usually not covered by a standard homeowners policy.
Does insurance pay to fix the pipe that leaked?
Usually not. Most policies pay for the damage the water caused — the ruined drywall, flooring, and belongings — but not for repairing or replacing the pipe, appliance, or roof that failed. The source of the leak is often your cost; the damage it caused is often the insurer's.
Is flood damage covered by homeowners insurance in Texas?
No. A standard Texas homeowners policy does not cover flood damage — water that rises from outside, like storm runoff or a rising creek. Flood damage needs separate flood insurance. Rain that comes in through a roof damaged by wind or hail is a different case and is often covered.
What should I document for a drywall water damage claim?
Take photos and video of the damage before anything is removed, keep the date and time, and get moisture meter readings in writing. Photos of the wet drywall, the water source, and any damaged belongings, plus a written repair estimate, give the adjuster what they need to work with.
How fast do I need to report water damage in Texas?
As soon as you find it. Report the damage to your insurer promptly, and take reasonable steps to stop more damage — shut off the water, move belongings, and get the area drying. Waiting weeks to report a leak you knew about can hurt a claim.
Need Help?
Call DeSoto Drywall Pros Before Anything Is Torn Out
Does homeowners insurance cover water damaged drywall? In Texas, sudden and accidental damage like a burst pipe is usually covered, gradual leaks and flood water usually are not, and the insurer typically pays for the damaged drywall — not for the pipe that failed. But coverage always depends on your policy, and no article can guarantee what your claim will pay. What we can guarantee is this: if your drywall got wet in DeSoto, TX, call (469) 933-0245 before anything is torn out. We will photograph the damage, take moisture readings in writing, and give you a detailed estimate you can hand to your adjuster — then repair the wall properly, dry the cavity, match the texture, and leave it paint-ready. We answer 24/7.